The quest to bring green regional aircraft to market is more likely to fail for financial than technical reasons, according to aviation consultancy Altea. In a white paper published on October 5, the UK-based group warns that investors in new aircraft and propulsion systems may lack the long-term commitment needed and that communities depending on the promised new air services could find themselves worse off if these fail.
"Clean-sheet aircraft programs can require eight to ten years or more to progress from design to entry into commercial service, while venture capital investors typically work against substantially shorter return horizons," Altea regional aviation specialist Chris Holliday concluded in the report. "This mismatch can provide a stronger indication of uncertain program resilience than propulsion technology alone," he wrote.
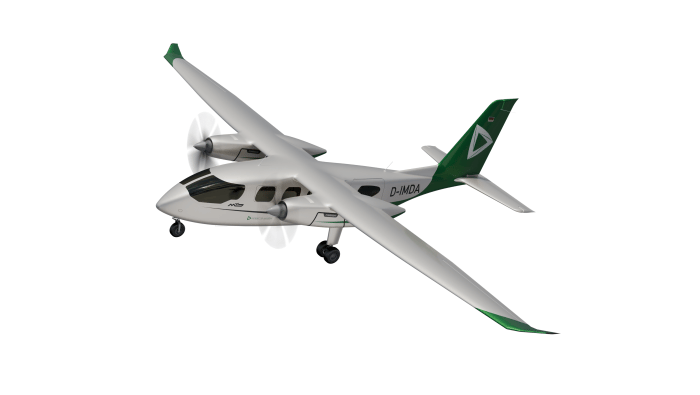
The white paper entitled The Real State of Alternative Propulsion for Regional Aviation addresses the viability of several start-ups in the sector, arguing that high-profile announcements about prospective aircraft orders should be viewed as less significant than more tangible measures of progress with programs and the solidity of capital backing. Altea's researchers have assessed companies including Heart Aerospace, Electra, Ampaire, ZeroAvia, Vaeridion, Elysian, and Jekta, on the basis of factors such as strategic investment, engineering capability, certification progress, manufacturing commitments, OEM support, and whether provisional sales agreements amount to deposit-backed orders.
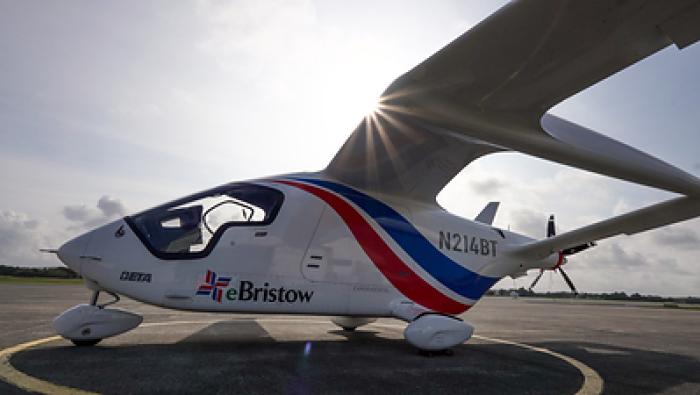
According to Altea, regional aviation start-ups are now more focused on battery-electric technology, while legacy OEMs such as Airbus, MTU Aero Engines and GKN Aerospace have the deep pockets needed to stick with hydrogen propulsion work for the as long as it may take to commercialize. Holliday pointed out that companies who retain direct control of battery supplies stand to generate significant revenue streams from the need for operators to replace these over the service life of aircraft and their propulsion systems.
For example, Beta Technologies has reported that one of its aircraft operating over two decades could need 18 to 20 sets of replacement batteries. This could amount to revenues of around $13 million, and Altea urged aircraft operators and leasing companies to pay attention to this cost factor when assessing business cases for the new technology.
While new and independent developers have been largely focused around battery-electric and hybrid powertrain architectures, project timescales are lengthening across the board. For instance, Altea believes Germany’s Vaeridion, developer of the all-electric nine-seat Microliner, has “technical credentials strong for its size” while notes its “commitments are largely paper.”
France’s Aura Aero “sits at the credibility end of this group, though not without some strain,” with first flight and entry into service now slipped to 2027 and 2029 respectively. The U.S.-based Electra is also “showing good progress across market and business development.”
Operational Considerations
However, battery weight remains a limitation. Holliday maintaained that as Part 23 aircraft—with 19 or fewer passenger seats and a maximum take off weight of 19,000 pounds—cannot simply get larger and heavier without slipping into the Part 25 category, “nearly every serious sub-30 seat program has [now] converged on some form of hybrid architecture.” Conversely, he also cautioned that a new aircraft staying under the Part 23 weight limit “is, by the same token, shutting itself out of Part 121 scheduled U.S. airline service and limiting itself to Part 135 commuter and on-demand operations instead.”
A case in point for Altea's white paper is Heart Aerospace, which revealed an updated 36-seat ES-36 aircraft last month: its fourth design iteration in six years. The company has decided to revert to the series-hybrid powertrain it first made about two years ago.
According to Altea, Heart’s move from a 19 to a 30 (and now 36) seat design traded more challenging performance expectations against an expectation of greater market relevance. “It accepted a heavier, more expensive certification basis in exchange for access to the scheduled airline market from which a lighter aircraft would have been barred,” explained Holliday.
Altea also highlighted significant risks for airlines looking to introduce the new aircraft, with many of these being start-ups too. If they fail, the consequences for customers could be impactful.
"Thin regional routes, island connections and essential air services represent natural markets for sub-30-seat electric and hybrid-electric aircraft," Holliday stated. "These services often have no fallback capacity if new technology runs into trouble, regardless of how well-resourced the operator flying them happens to be."
The report cautioned that certification of a “genuinely new propulsion architecture and platforms” takes eight to ten years or more from clean-sheet design to entry into service, whereas venture capital is built around a five to seven year return horizon. “Put bluntly, the capital structure funding most of this sector is not built to reward the companies most likely to succeed. It is built to reward whichever company can tell the most convincing five-year story,” Holliday suggested.
Operational considerations of these aircraft is also relevant to this perceived mismatch between investor patience and certification reality, according to Holliday. Whereas the addressable market for most sub-30 seat electric and hybrid platforms is thin, often-subsidized and regional routes and island connectivity,” these are “precisely the operators least equipped to absorb new-technology risk.” Projected operating costs could also warrant further scrutiny, with quoted figures often “statements by a manufacturer and a prospective customer rather than independent findings.”
More In Sustainability and Environment