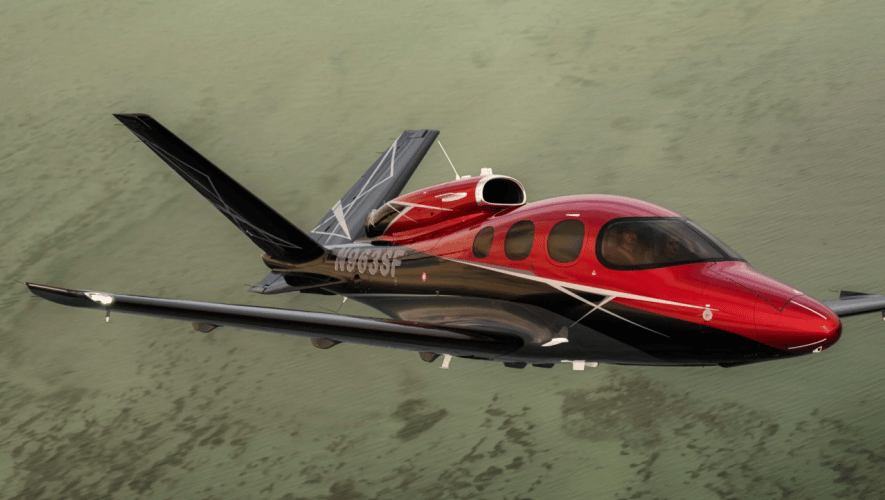
Honeywell Aerospace’s 35th annual Global Business Aviation Outlook predicts deliveries of 9,950 business jets and 4,200 turboprops over the next decade. Released on Monday, the forecast considers personal jets such as the Cirrus Vision Jet, as well as business turboprops, for the first time. The outlook examines fleet usage and operator expectations.
“In the past, it was only deliveries and only business jets,” Honeywell Aerospace strategic planning manager Kevin Schwab told AIN. “What we’re trying to accomplish is to help the industry understand where we sort of stand today, where we think we’re going into the future, so that everybody can sort of adequately plan and prepare, and sort of have some transparency around where we think the sector is going, and we thought that excluding some of the segments of the industry was doing a little bit of a disservice to that goal.”
Over the 10-year forecast window, the company, which spun off from parent company Honeywell earlier this year, sees approximately 14,000 deliveries of business aircraft in total. The expected 9,950 jet shipments are up 4.4% from last year’s outlook.
For this year, Honweywell foresees 1,280 new-production aircraft deliveries as OEMs continue to work through years-long backlogs, rising to more than 1,500 a year by 2035, at an estimated value of $37 billion annually, with large cabin jets representing the largest share.
“We are seeing an increase in the forecasted number of aircraft,” explained Schwab. “This is partially due to some of the growth that we have seen over the last couple of years, and some of the orders that have already come in, but also over the last year, we have a relatively strong economic outlook.” He further noted the strong growth in the number of high-net-worth individuals, particularly in the U.S., as a factor driving the market.
As part of its annual outlook preparations, Honeywell Aerospace generates its buyer expectation survey, which it sends to hundreds of non-fractional business aircraft operators. This year, more than a quarter of the respondents—who represent more than 1,500 business aircraft worldwide—indicated that they have at least one new aircraft on firm order.
By 2035, Honeywell Aerospace expects the global fleet to number 18,000 turboprops, 15,000 light jets, 8,200 midsize jets, and 9,700 large cabin jets. With their intercontinental capability and reduced price and operating costs versus larger aircraft, midsize jets are anticipated to grow more than 40% during the forecast period, outpacing all other segments.
“What we see over the next 10 years is about 29% growth in the overall global fleet,” Schwab told AIN. “This is more than there had been over the last 10 years, and this is driven by two factors that are working together. Number one, deliveries are higher now, and we’re anticipating them to be higher over the next 10 years. Also, retirements are lower—they have been a little bit lower the last couple of years—and we’re expecting them to be lower moving forward.”
Schwab noted the decrease in aircraft retirements continues a trend seen in the industry post-pandemic, when many aircraft operators chose to make the repairs, inspections, and upgrades on older aircraft that wouldn’t have been justifiable a few years earlier.
“Usually, you choose to retire an aircraft when it makes when it no longer makes economical sense to do so,” said Schwab. “But if you have scarcity of assets, and an industry which has a relatively large willingness to pay to use it, the economic balance changed a bit.
“They were willing to pay for that extra shop visit, or get that extra upgrade to keep the aircraft flying longer because there was somebody willing to buy that airplane and there was somebody willing to still fly that airplane.” He expects that dynamic to continue for at least the next five years.
With the expansion of the global fleet from 39,400 aircraft in 2025 to nearly 51,000 predicted by 2035, Schwab believes that rising tide will lift all boats, in terms of ancillary businesses such as FBOs and MROs.
Not only will there be more aircraft, but they will be busier, according to the OEM. The report notes that business aviation is increasingly shifting toward operating models that maximize aircraft usage, enabling flight activity to grow faster than the underlying fleet. Total industry flight hours are predicted to increase by 34% over the forecast period due to that increased usage and fleet increases.
While private operators continue to represent the majority of aircraft ownership, charter and fractional operators account for a disproportionate share of utilization because their aircraft are flown at much higher rates. However, nine out of 10 non-fractional survey respondents indicated that they expected to fly as much as next year as they did in 2026, if not more.
In terms of purchase priorities, while performance remained the top driver, followed by cost, Schwab was surprised by the results of this year’s survey, which indicated that cabin experience is now tied for second place.
“This is things like cabin noise, vibrations, the overall design of the cabin, amenities like the galley and lavatory space, interior baggage storage, and the cabin management systems,” he said. “I think that some of the wealth creation and some of the new users of business aviation, due to wealth growth, are driving a portion of them to prioritize cabin experience, at least at the same level as cost.”
The U.S. and Canada account for 63% of global deliveries and 68% of worldwide business aviation flight hours. The region is also the leader in shared use operating models, accounting for approximately 83% of global fractional flight activity. The survey results show confidence among operators, with nearly one-third planning to expand their fleets over the next five years.
Latin America, host to the world’s second-largest business aviation fleet, accounts for 14% of global deliveries, primarily in Mexico and Brazil. Schwab noted that the growing EU-Mercosur trade agreement could spur business travel between South America and Europe, along with other international routes. The area has strong fleet expansion intentions, indicating operators there are optimistic about long-term growth.
While Europe represents 10% of the global fleet, it has 13% of global flight activity. The region has strong leisure travel demand and rising interest in flexible aviation solutions, but it faces some headwinds due to regulatory pressure, sustainability requirements, and geopolitical uncertainties. Yet operator sentiment remains positive, with many organizations indicating willingness to expand their fleet capacity.
The Middle East has seen setbacks due to the ongoing Iran war. “The Middle East was really one of the stronger growth regions, and that was growth that was long-term and sustainable in our view. It was not temporary by any means,” said Schwab. He pointed to the recent improvements in infrastructure and regulations in places such as the UAE and Saudi Arabia. “These are long-term plans and long-term investments, and we expect that long-term growth in the Middle East for business aviation is going to continue once the conflict subsides.”
In the Asia-Pacific region, Schwab noted that the market is continuing to expand in India. “It’s a very small portion of business aviation today, but the government is trying to improve the ability of business aviation to take foot in the country,” he explained. “I think it makes a lot of sense for a lot of reasons. It’s a very large country geographically, which is well suited to aviation; it has major business centers with major corporations that use business aviation to get to their different facilities; [and] they also have their own major corporations that have different sites within the country.”
In this article
More In Aircraft