Amstat has identified significant variations in market conditions based on its latest assessment of preowned aircraft values at the end of the third quarter. In its latest market update, released today, it noted tighter supply and rising prices for heavy- and super-midsize business jets, but “softer transaction activity” for other categories, including midsize and light jets, as well as turboprops.
According to Amstat, available heavy-jet inventory appears to have plateaued after availability contracted in the first half. As of September 30, it calculated that 5.1% of this fleet is on the market, compared with a 10-year average rate of 7%. Options for buyers in this market segment were even more limited for newer models.
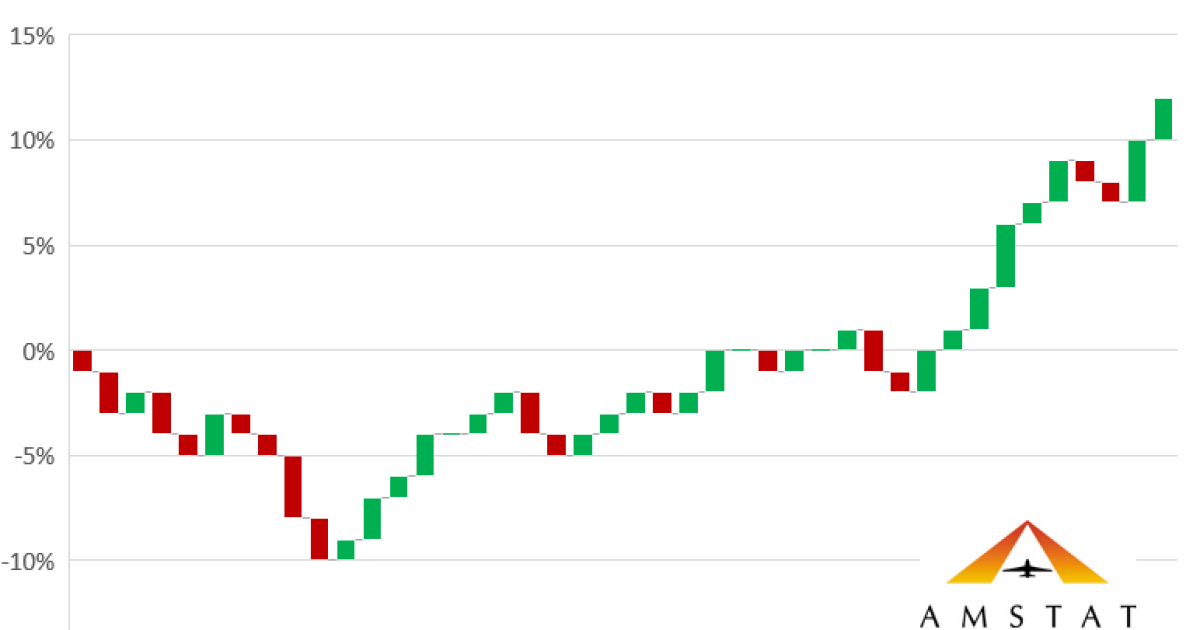
Amstat said overall transaction activity has remained robust. “Through the end of the third quarter, year-to-date transactions were 7.3% higher than the same period in 2025,” the New Jersey-based group reported. “Tight supply and strong demand continue to put upward pressure on values: the median value of preowned heavy jets is up 14% year to date.”
By contrast, Amstat said super-midsize jet inventory is 11.4% higher year to date than in 2025. With transaction activity remaining strong at 11.7% above the same period last year, median values recently leveled off and are now only 2% higher.
Inventory for midsize jets is now around 10% higher, but transaction activity has dipped in this category. Amstat’s preliminary third-quarter data shows year-to-date sales in this segment as being 6% behind 2025, with median values up by 4%.
Preowned light jet inventory has remained fairly stable with around 7% of this fleet for sale, below the 10-year average of 8.9%. After a strong first half, transactions declined 26% in the third quarter, Amstat reported, with year-to-date activity lagging 6.2% from a year ago.
Conversely, the inventory of available turboprop aircraft increased over the summer months, after falling previously. Currently, around 5% of the fleet is on the market, which is close to the 10-year average of 5.8%.
Third-quarter turboprop transactions fell 47%, and Amstat indicated that year-to-date activity is around 9% below the same period last year. The pace of decline in values for turboprops has slowed this year but is still down, falling 5% year to date.
“While we still have Q3 data coming in, the data so far indicates that the market is moving in different directions by segment,” Amstat general manager Andrew Young concluded. “Heavy and super-midsize jets continue to benefit from limited supply and strong demand, while transactions have softened in the third quarter for midsize jets, light jets, and turboprops.”
In this article
More In Finance, Taxes, Insurance